BRX NewsretailOctober 30, 2026
Black Friday Grows, Traditional Retail Suffers: Consumption Has Changed Address
Projections indicate a heated Black Friday in 2026 while major chains face financial difficulties. The contrast reveals a structural transformation: demand continues to exist, but it is migrating to more efficient, digital, and scalable models.
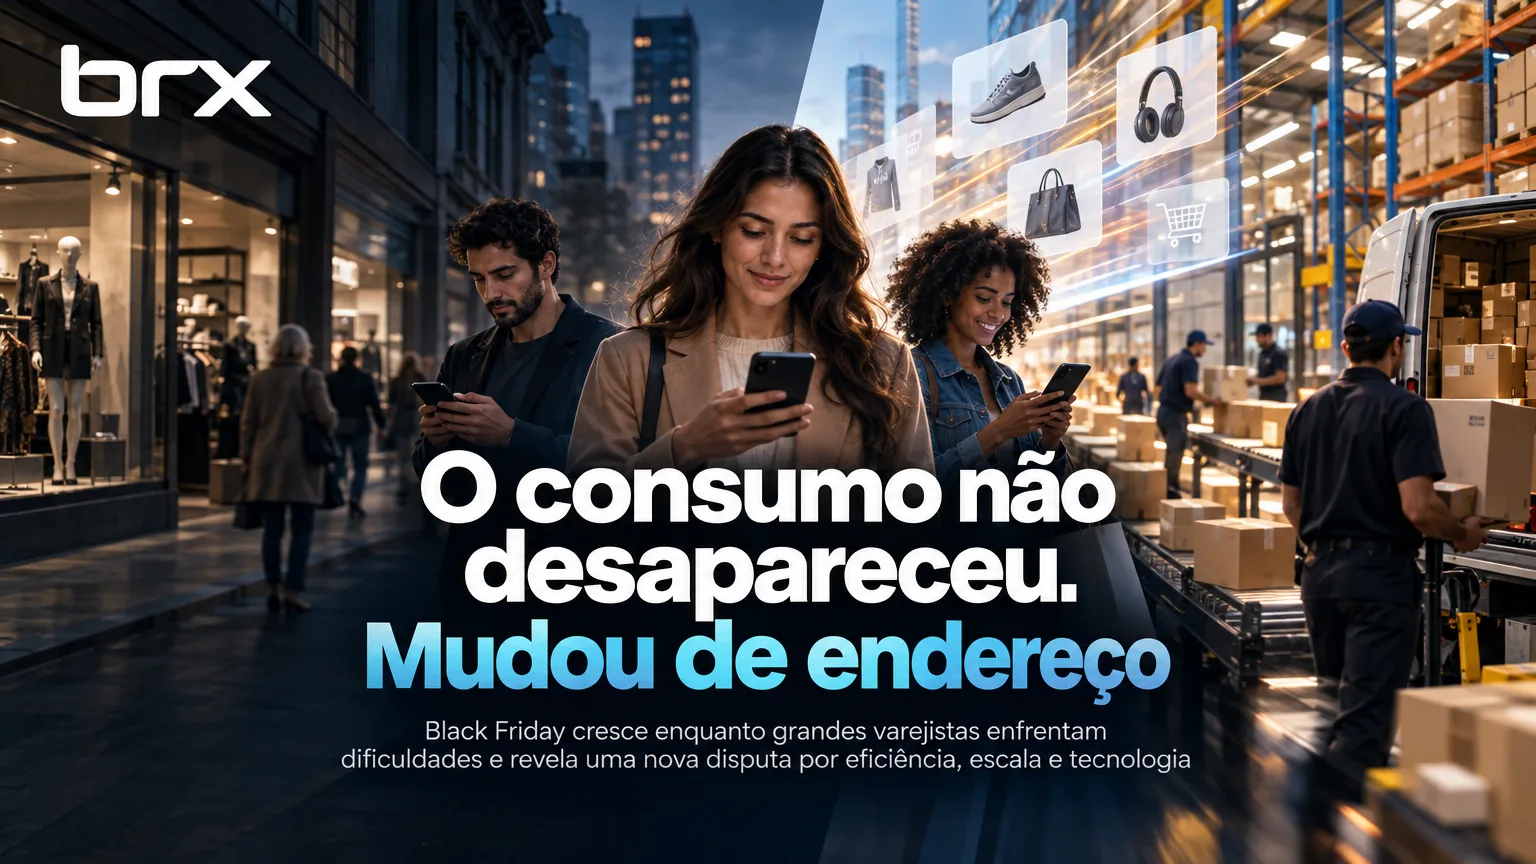
Projections indicate a heated Black Friday in 2026 while major chains face financial difficulties. The contrast reveals a structural transformation: demand continues to exist, but it is migrating to more efficient, digital, and scalable models.
The Black Friday of 2026 is expected to confirm an apparent contradiction in Brazilian retail.
On one side, large companies are undergoing financial restructuring processes, strategic reviews, or struggling to regain profitability.
On the other, expectations for e-commerce remain positive.
Confi, through Neotrust and in partnership with E-Commerce Brasil, projects that Brazilian e-commerce will generate R$ 13.3 billion between November 26 and 29, a growth of 20.7% over the same four days in 2025. The expectation is approximately 69.4 million products sold, an increase of 15.4%.
In logistics, DHL Supply Chain expects to move 27% more goods during its Peak Season of 2026, a period that encompasses the months of October to December, with November being the main concentration of demand.
How can a market grow while relevant companies in the sector face difficulties?
The answer helps to understand one of the biggest transformations underway in retail:
Consumption has not necessarily disappeared. It has changed address.
A company's crisis does not mean a demand crisis
Market revenue and the financial health of companies are different things.
A consumer can continue to buy while completely changing where, how, and from whom they buy.
It is precisely this movement that helps explain the current scenario.
Marketplaces, digital platforms, and large-scale operators have been capturing an increasing share of consumption by combining attributes that have become decisive for the customer:
- variety;
- instant price comparison;
- convenience;
- delivery speed;
- stock availability;
- ease of payment;
- digital experience;
- trust in delivery and after-sales.
Meanwhile, companies built on predominantly physical structures must manage occupancy costs, personnel, inventory, and capital while undergoing their own digital transformation.
The problem, therefore, is not necessarily the absence of consumers.
It is in the competition for who can serve them more efficiently.
Scale has begun to produce even more scale
The numbers from large platforms help visualize this change.
In the second quarter of 2026, Mercado Livre recorded approximately US$ 22 billion in global GMV and reached around 89 million active unique buyers. In Brazil, GMV grew 39% in constant currency, and the number of items sold increased by 56% year-on-year.
This growth creates a cycle that is difficult to replicate.
The larger the platform, the greater its ability to bring together consumers and sellers. With more transactions, data availability increases, logistics infrastructure utilization improves, and the capacity to invest in technology grows.
More scale can allow for better prices, faster deliveries, and more convenient experiences.
These advantages, in turn, attract more consumers.
It is a feedback loop that increases the distance between companies capable of operating at scale and organizations that still deal with fragmented processes.
The problem is not having physical stores
The expansion of e-commerce does not mean that the physical store has lost relevance.
The central point is different.
A chain of stores can be a huge operational liability or a powerful competitive advantage, depending on how it is connected to the rest of the operation.
An integrated store can function simultaneously as:
- point of sale;
- pickup point;
- return location;
- advanced inventory;
- source of digital orders;
- consumer relationship space;
- short-distance fulfillment point.
But this only works when there is adequate visibility of inventories, channel integration, and consistent processes.
Without this connection, the company may face a paradoxical situation: having the product within the network and still losing the sale because it cannot make it available correctly to the consumer.
Inventory has become a matter of intelligence
In periods like Black Friday, availability is a competitive advantage.
But simply increasing inventory does not solve the problem.
Excess inventory consumes capital, increases financial costs, and creates markdown risk. Insufficient inventory causes stockouts and lost sales.
The challenge is to position the right product, in the right quantity, and in the right location.
This requires increasingly sophisticated decisions about:
- demand forecasting;
- assortment;
- planning;
- replenishment;
- distribution;
- transfers;
- allocation;
- availability by channel.
When thousands of products are distributed across dozens or hundreds of stores, distribution centers, and digital channels, seemingly small decisions can represent millions of reais in capital employed.
Black Friday tests much more than e-commerce
Promotional dates are often treated as a challenge of the website's technological capacity.
But a major campaign tests practically the entire retail chain.
A promotion can generate extraordinary traffic and still produce little result if inventory is poorly distributed, margins have been poorly calculated, or logistics cannot fulfill the promise made to the customer.
Therefore, performance on Black Friday should not be measured solely by sales growth.
It is also necessary to observe margin, turnover, availability, conversion, fulfillment cost, and cash generation.
Growing without profitability also does not solve
The Brazilian scenario itself shows that growth in GMV or digital share is not enough.
Magazine Luiza, for example, recorded GMV of R$ 14.5 billion in the second quarter of 2026, while its management chose to prioritize profitability, margin, and cash generation instead of simply pursuing volume.
This discussion is particularly important in a high-interest environment.
Inventory costs money.
Working capital costs money.
Infrastructure costs money.
Customer acquisition costs money.
And inadequately financed growth can destroy value even when sales increase.
The new game of retail is not simply selling more.
It is selling better.
The true paradox
Perhaps, therefore, there is no paradox between a strong Black Friday and struggling retailers.
Both movements may be part of the same transformation.
Demand continues to be present, but it is being redistributed among companies with different competitive capabilities.
Consumers have begun to compare prices in seconds, demand virtually immediate availability, and expect a consistent experience across physical and digital channels.
In this environment, scale helps.
But scale without efficiency is also costly.
Winners tend to be those capable of combining four elements:
data, inventory, technology, and operational execution.
The next retail battle will be for efficiency
Projections for Black Friday 2026 show that there is still significant consumption in the Brazilian market.
The strategic question for retailers is who will be able to capture this demand profitably.
For many years, digital transformation primarily meant creating an e-commerce platform.
That stage is behind us.
Transformation is now happening at the core of the operation: planning, merchandising, inventory, pricing, stores, logistics, and channel integration.
In today's retail, it is not enough to be present where the consumer shops.
It is necessary to have the right product, in the right place, at the right price — and to be able to fulfill the promise made to the customer with margin.
Perhaps this is the main message behind the apparent Brazilian paradox:
Retail is not running out of consumers. It is becoming increasingly intolerant of inefficiency.
Retail is not running out of consumers. It is becoming increasingly intolerant of inefficiency.